Oil & Gas Buyer Types: The 8 People You're Actually Selling To
A field map of the eight buyer types inside oil and gas companies — what each cares about, the question they ask, and what wins them — drawn from 80+ podcast episodes and ModalPoint buyer research.
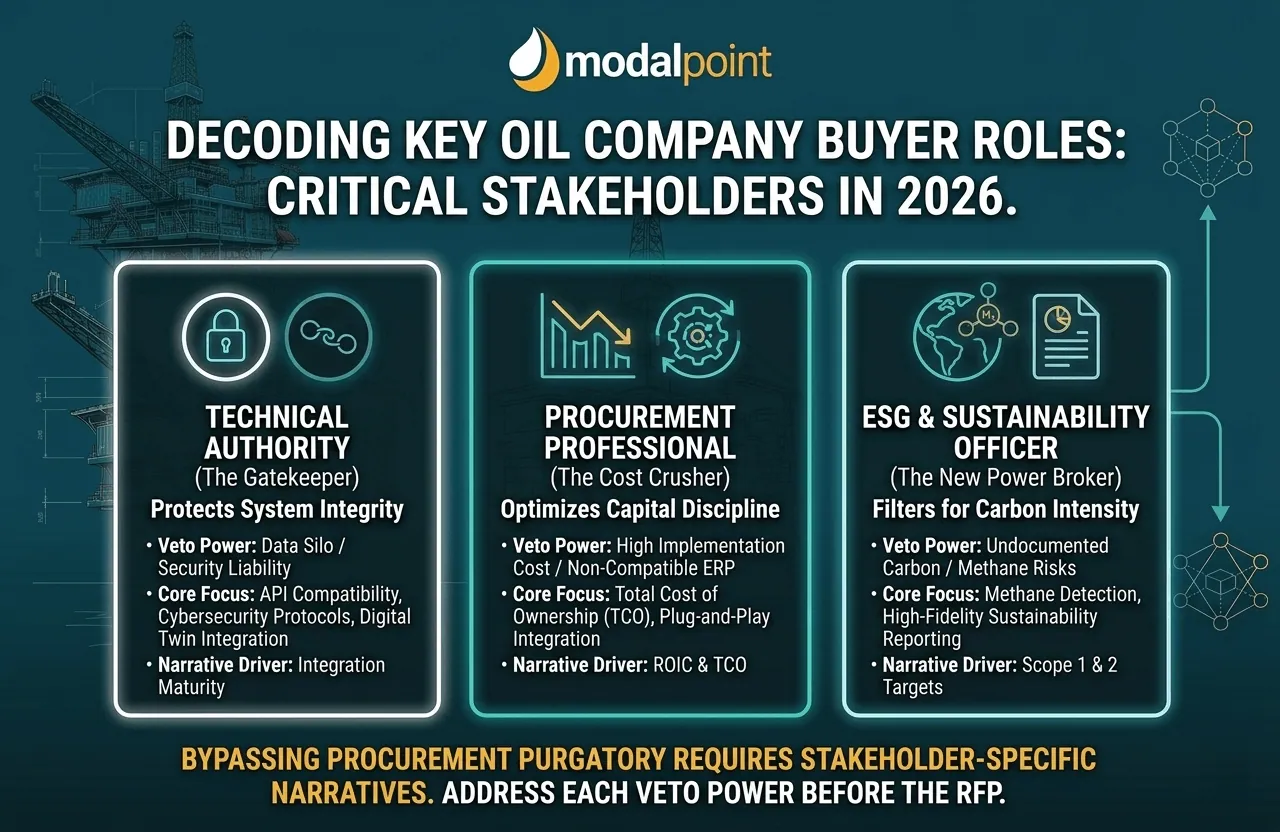
A field map of the eight buyer types inside oil and gas companies — what each cares about, the question they’re silently asking, and what actually wins them over.
Companies don't buy anything — people do. If you sell into oil and gas, you're selling to a committee of people with different jobs, different risks, and different definitions of a good decision, and deals die when any one of them is ignored.
The patterns here are drawn from 80+ episodes of the Oil and Gas Sales and Marketing Podcast, hosted by ModalPoint president Matt Bertram, plus ModalPoint's structured buyer-research interviews and route-to-market validation work. ModalPoint turns this map into named-account plans for companies selling into energy.
Selling into oil & gas? We’ll tell you which seat at the table is your actual blocker.
Twenty conversations are cheaper than a mistargeted year of selling. Want proof first? See the Tamboran route-to-market case study.
Why buyer types matter more in oil & gas than almost anywhere else
Three structural facts shape every sale in this industry. Risk is the primary filter — the downside of a bad purchase (downtime, injury, environmental release) dwarfs the upside of a good one, so every buyer type screens for risk before value. Buying committees are large and real — a mid-size purchase can touch engineering, operations, IT, procurement, HSE, and finance before an executive ever sees it. And sales cycles are long and non-linear, which means you'll meet all of these people eventually; the only question is whether you meet them on purpose. For the process itself, see how oil & gas companies buy; for the strategy layer, see how to sell into the oil & gas industry.
The eight buyer types
Click any card to expand it. Prefer it on one page? Download the buyer map (PDF) and share it with your team.
Entry points The gates The money seats Emerging
Jump to: Engineering · Operations · IT & cyber · Procurement · HSE · Executive · Finance · AI & digital
1. Engineering & technical authority
The feasibility gate. Nothing advances until they believe it works.
Who they are: Discipline engineers, facility engineers, and technical subject-matter experts. They rarely hold the budget, but they hold the credibility the rest of the committee leans on. When an executive asks “will this work?”, this is who answers.
What they care about: Specs, standards compliance, and performance under their operating conditions — not yours. They think in tolerances, failure modes, and what happened the last time someone brought in something unproven.
The question they're asking: “Will this actually work in our environment?”
What wins them: Data sheets, pilot results on comparable assets, and engineering support that speaks their discipline. References from operators running similar equipment in similar service carry more weight than any marketing claim.
Where sellers go wrong: Sending marketing to do an engineer's job. ROI decks bounce off this group. If your first meeting doesn't include someone who can answer a technical question directly, you've told them everything they need to know about you.
2. Operations & OT leadership
The uptime owner. They buy risk reduction, not innovation.
Who they are: Operations VPs, superintendents, and facility leads — the people who own whether the plant runs. Their vocabulary is turnarounds, management of change, SCADA, and interlocks, and their default vendors have been in the facility for decades.
What they care about: Reliability, safety, and production. A day of unplanned downtime can erase the annual value of whatever you're selling, so their bias against change is rational, not stubborn.
The question they're asking: “Will this disrupt production?”
What wins them: Uptime evidence, peer references from operators they know, and an implementation plan that respects their turnaround schedule and MOC process. The strongest operator framing we've heard is blunt: nobody gets hurt, and we don't lose a barrel.
Where sellers go wrong: Pitching innovation to people who are paid to prevent surprises. Novelty is a cost to this buyer, not a feature. Show them you understand their change-management process before you show them your product.
3. IT & cybersecurity
The late-stage veto. They decide what crosses the firewall.
Who they are: IT directors and CISOs, reporting up through the CIO toward the CFO and the board's audit and risk committee. They own endpoints, data residency, network access, and vendor security review.
What they care about: What your product connects to, where the data goes, and who can see it. Energy companies are critical infrastructure; their security reviews are correspondingly unforgiving.
The question they're asking: “What does this touch, and who can see the data?”
What wins them: A clean security posture (SOC 2 or equivalent), a clear deployment architecture, and flexibility on where processing happens — the industry is actively pulling data and decisions back on-prem and to the edge, so “runs against your infrastructure” beats “send us your data.”
Where sellers go wrong: Treating IT as a rubber stamp after the operational deal is done. They can and do veto at the finish line. Bring them in early, hand them the architecture diagram before they ask for it.
4. Procurement & supply chain
The qualification gate. They control whether you can be paid at all.
Who they are: Procurement managers, category managers, and supply-chain leads. They administer the approved vendor list, master service agreements, and commercial terms.
What they care about: Vendor qualification, insurance and safety prequalification (ISNetworld and its cousins), financial stability, and pricing they can defend internally. They are measured on risk and cost, not on your product's upside.
The question they're asking: “Does this vendor meet our standards and terms?”
What wins them: A clean, complete prequalification package the first time, clear terms without exotic clauses, and patience with a process that exists for reasons that predate you.
Where sellers go wrong: Trying to go around them — or mistaking them for the economic buyer and pitching value to a gate whose job is compliance. Procurement can stop a deal; they almost never start one. Win the committee first, then make procurement's job easy.
5. HSE leadership
The safety conscience. A quiet veto that outranks enthusiasm.
Who they are: Health, safety, and environment managers and directors. In an industry where the worst outcome is a fatality or an environmental release, HSE review is structural, not ceremonial.
What they care about: Whether your product, people, or process introduces risk to workers, the environment, or the company's permits and regulatory standing. Your own safety record is part of their evaluation.
The question they're asking: “Does this add risk to people, the environment, or our compliance position?”
What wins them: A credible safety record (they will ask for your TRIR), relevant certifications, and a rollout plan compatible with their management-of-change requirements. Evidence you've worked safely on sites like theirs is the fastest trust-builder available.
Where sellers go wrong: Treating the safety review as paperwork to be endured. Sellers who engage HSE with the same seriousness they give the economic buyer are rare enough to be memorable.
6. Executive & commercial leadership
The economic buyer. They fund a business case, not a technology.
Who they are: C-suite executives, business-unit VPs, and commercial leads. Depending on deal size they are either the final signature or the sponsor who defends the spend to the board.
What they care about: Return on investment, strategic fit, and capital discipline. The post-2020 energy market rewards executives for returning capital, not for spending it — every dollar you ask for competes against a buyback or a dividend.
The question they're asking: “Is this worth the investment right now?”
What wins them: A quantified business case in their units — barrels, downtime hours, safety incidents, dollars — that a sponsor can carry into a room you'll never enter. Timing matters: land the case when budgets form, not after they're locked.
Where sellers go wrong: Leading with technology and expecting the executive to translate it into value. That translation is your job. If your champion can't state the payback in one sentence, the deal stalls in internal alignment.
7. Finance & ownership
The capital allocator. At PE-backed operators, the real power seat.
Who they are: CFOs, VPs of finance, and — at private-equity-backed operators — the sponsor's operating partners. A large share of US independents are PE-owned, which changes how buying decisions actually get made.
What they care about: Cash flow, payback period, and increasingly what your product does to the company's position at exit or transaction time. PE-backed operators decide faster than supermajors but scrutinize harder, because every line item surfaces in diligence.
The question they're asking: “What does this do to cash flow, and what happens at exit?”
What wins them: Payback inside their hold-period math, pricing structures that flex with commodity cycles, and references from other portfolio companies — sponsors talk to each other, and one good deployment can travel across a whole portfolio.
Where sellers go wrong: Assuming budget exists because interest does. Capital allocation runs on cycles and thresholds; a deal that misses the budget window waits a year, no matter how enthusiastic the operational team is.
8. The AI & digital owner
The newest seat at the table — and often the least defined.
Who they are: Digital transformation leads, data and analytics heads, and newly formed AI departments. This role sits in the seam between IT and OT, and at many operators nobody formally owns it yet.
What they care about: Depends on maturity. Most energy companies are still in the “use AI to be more productive” phase: informal mandates, a sanctioned tool, no formal goals. The leading firms are moving toward formal AI targets, policies, and eventually board-level accountability for what AI systems decide.
The question they're asking: “Who owns this decision, and can we prove it?”
What wins them: Concrete, bounded use cases with measurable productivity gains today, plus a credible path to governance as their board starts asking exposure questions. Operator language first — efficiency, uptime, safety — compliance language later.
Where sellers go wrong: Pitching governance maturity to a company still in the productivity phase, or assuming this buyer has budget authority. Early on they are a champion, not an economic buyer — sell them the future, close with the executive.
Same title, different company: how buyer types shift by company type
A VP of Operations at a supermajor and a VP of Operations at a PE-backed independent hold the same title and buy in completely different ways. Before you apply the map above, adjust for who owns the company.
Supermajors & large independents
Committee-heavy, process-driven, and slow by design. Expect long qualification cycles, sanctioned-tool cultures, and pilots that move at the speed of the turnaround calendar. The buyer types above all exist here in full force, and internal alignment — not any single yes — is the real sale. Hard to enter; durable once you're in.
PE-backed independents
Fewer layers, faster decisions, and a finance seat with unusual power. The CFO and sponsor's operating partners weigh in early, and transaction-readiness colors every purchase. A supermajor sales motion aimed at a PE-backed operator will feel bloated; a sharp payback story aimed at the right two people can close in weeks.
Oilfield services & equipment companies
When you sell to the service sector, the commercial and operations seats dominate. These companies live on margin and utilization, so they adopt what helps them win or deliver work — and they feel commodity cycles first. Price sensitivity is higher, but so is willingness to move fast on anything tied to revenue.
EPCs & engineering firms
Project-driven buyers. Purchasing decisions attach to specific projects and their specs, so the engineering seat is your entry point: the engineer who specifies you into a design has effectively bought for you. Qualification is long, project cycles are unforgiving, but a spec position compounds across future projects.
How to use this map
- Map the committee before the first meeting. For any target account, name the likely person in each seat above. Empty seats on your map are where deals die.
- Match the message to the seat. Specs for engineers, uptime for operations, architecture for IT, payback for executives. One deck for everyone is a deck for no one.
- Enter through credibility, close through the business case. Technical trust opens the door; a quantified case your champion can carry gets it signed.
- Sequence, don't broadcast. The committee aligns in an order — usually technical, then operational, then commercial, with procurement, IT, and HSE as gates along the way. Selling out of order creates internal antibodies.
- Validate before you commit. Assumptions about who your buyer is are usually wrong until tested. In one ModalPoint route-to-market validation, fifteen structured interviews overturned a client's core assumption about which seat held the intent. Twenty conversations are cheaper than a year of mistargeted selling.
Selling into oil & gas? We’ll tell you which seat at the table is your actual blocker.
Twenty conversations are cheaper than a mistargeted year of selling. Want proof first? See the Tamboran route-to-market case study.
Frequently asked questions
Which buyer type matters most?
None of them alone. Oil and gas deals close on alignment: each buyer type evaluates a different risk and can stop the deal for a different reason. The economic buyer signs, but a technical no, a security no, or a safety no upstream of them usually means the signature never happens. Map all the seats before you invest heavily in any one of them.
Who should we contact first?
Usually the engineering or operations seat, because credibility with them is the currency the rest of the committee accepts — but your entry point is not your decision-maker. The productive pattern is to build technical credibility first while mapping the full committee, then equip an internal champion to carry a quantified case to the executive seat. That mapping step is where a structured buyer-research pass typically pays for itself.
How different is selling to a PE-backed operator versus a supermajor?
Structurally different. Supermajors buy by committee and process; PE-backed operators buy on capital discipline and speed, with the finance and ownership seat carrying far more weight. The same product may need a reliability-and-process story at a major and a payback-and-exit story at a sponsor-backed independent.
Do these buyer types apply to selling software and AI into oil and gas?
Yes, with two amplifications: the IT and cybersecurity seat gets a harder veto, and the AI and digital owner moves from peripheral to central. Most energy companies are still early in AI adoption — informal productivity mandates rather than formal governance — so meet that buyer where they are rather than where the technology conversation suggests they should be.
Selling into oil & gas? We can help
ModalPoint maps buyer committees for a living — structured buyer-research interviews, route-to-market validation, and go-to-market strategy built specifically for companies selling into the energy sector.
Selling into oil & gas? We’ll tell you which seat at the table is your actual blocker.
Twenty conversations are cheaper than a mistargeted year of selling. Want proof first? See the Tamboran route-to-market case study.
Not ready to talk? Build your target list in our directory of oil & gas companies first, and come back when you have named accounts.
We publish what we learn, every week.
Much of how we read the energy buyer comes from the show Mark LaCour and Matthew Bertramhost on the Oil & Gas Global Network — 99 episodes with the sales leaders, marketers, and operators who actually close deals in energy. It is the working notebook behind the advisory.
- How energy buyers actually evaluate vendors
- What earns a meeting with an operator
- Where marketing loses the technical buyer
Talk to ModalPoint
A 30-minute call to see if ModalPoint is the right firm and whether the timing makes sense. No obligation either way.